
Insurance for Home Health Care and Non‑Medical Home Care Businesses
Every day, thousands of families across Nevada invite caregivers into their private homes to look after their most vulnerable loved ones. As the population ages, the demand for these services is skyrocketing. Recent market projections suggest the United States home healthcare sector will experience massive, sustained growth through the next decade.
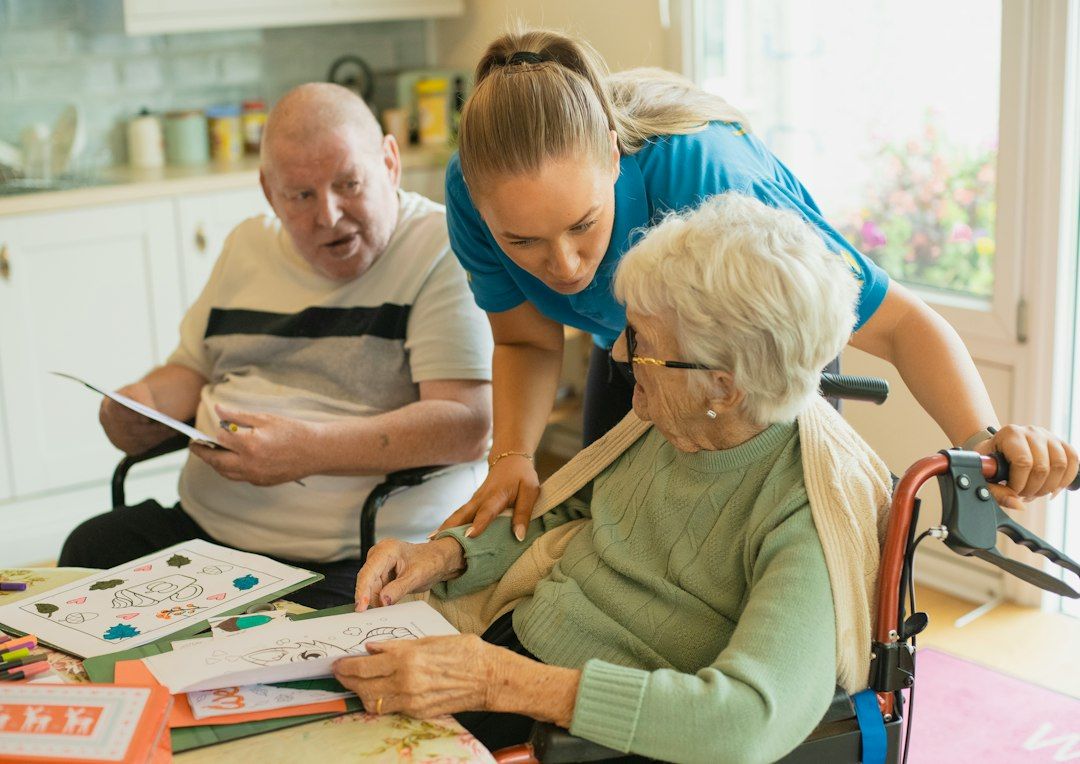
The Rising Demand and Unique Risks of In-Home Care
Every day, thousands of families across Nevada invite caregivers into their private homes to look after their most vulnerable loved ones. As the population ages, the demand for these services is skyrocketing. Recent market projections suggest the United States home healthcare sector will experience massive, sustained growth through the next decade, driven largely by a cultural preference for aging in place and remarkable advances in remote patient monitoring.
However, providing care inside a private residence introduces a highly unpredictable set of risks. Unlike a controlled hospital or clinical environment, a client's home is full of variables that an agency owner cannot easily manage. A caregiver might encounter loose rugs, aggressive family pets, or poorly maintained medical equipment. At Larry Peyton Insurance Agency, we have spent over 50 years helping local business owners protect their livelihoods and their employees. In our experience, securing the right coverage is about much more than just checking a compliance box. It is about safeguarding your ability to deliver peace of mind to the families you serve. Whether your staff provides highly skilled nursing or non-medical personal assistance, understanding your unique risk profile is the first step toward building a resilient, long-lasting agency.
The Evolving Landscape of In-Home Care in Nevada
Before building a risk management strategy, it is important to clearly distinguish between the two primary models of in-home care, as they dictate your specific regulatory and coverage needs.
The first category is home health care. This involves skilled medical services provided by licensed professionals, such as registered nurses, physical therapists, and occupational therapists. These services are often prescribed by a doctor, paid for by Medicare or private health insurance, and involve clinical interventions like wound care, administering intravenous medications, or monitoring vital signs.
The second category is non-medical home care. This model relies on personal care aides and caregivers who assist clients with activities of daily living. These activities include bathing, dressing, meal preparation, light housekeeping, and general companionship. While these caregivers do not provide medical treatments, their role is physically demanding and involves a high degree of trust and responsibility.
In Nevada, the state regulates and licenses these two categories separately. Finding the right insurance for home care business operations versus skilled medical models requires a deep understanding of these legal distinctions. Furthermore, the regulatory environment in our state has become increasingly strict. For example, in June 2026, the Nevada Health Authority implemented a temporary moratorium on new state licenses for home health and hospice providers, along with a pause on new Nevada Medicaid enrollments. This decisive action was taken to audit existing providers, root out fraudulent billing practices, and protect taxpayer funds.
For legitimate, hardworking agency owners, this level of regulatory scrutiny underscores the importance of running a flawless operation. State regulators, healthcare partners, and prospective clients are all looking for indicators of credibility. Maintaining comprehensive types of insurance every Nevada small business should consider demonstrates that your agency is financially stable, fully compliant, and prepared for the unexpected. When you invest in quality business insurance in the healthcare sector, you are actively protecting your reputation in a highly competitive market.
Core Coverages for Your Agency
Because caregivers operate independently in varying environments, standard business policies are rarely enough. A well-structured insurance portfolio must address the specific physical, professional, and digital risks your staff faces every day.
General Liability Insurance
General liability is the foundation of any commercial insurance package. It protects your agency against claims of third-party bodily injury and property damage. Because your employees are constantly working in someone else's home, the risk of accidental property damage is exceptionally high. If a caregiver accidentally knocks over an expensive antique vase, spills a beverage on a high-end laptop, or fails to turn off a stove and causes a kitchen fire, general liability coverage steps in to handle the costs of repair or replacement. It also covers third-party injuries, such as a visiting family member tripping over a caregiver's medical bag left in a hallway.
Professional Liability Insurance
While general liability covers physical accidents, it does not cover mistakes made in the actual delivery of care. To fully protect your agency, you must secure General liability vs. professional liability for small businesses coverage. Often referred to as medical malpractice or Errors and Omissions insurance, small business professional liability insurance is critical for both skilled and non-medical agencies.
For a skilled nursing agency, professional liability covers allegations of medical negligence, such as administering the wrong dosage of a medication or failing to properly document a declining vital sign. For a non-medical agency, this coverage is equally vital. If a personal care aide improperly transfers a client from a bed to a wheelchair, resulting in a severe fall and a broken hip, the family will likely sue the agency for negligence. This is exactly where home health liability insurance proves its worth, covering legal defense fees, court costs, and eventual settlements or judgments.
Workers' Compensation
Caregiving is a physically demanding profession. Aides routinely lift, turn, and support adult clients, which frequently leads to severe musculoskeletal injuries, chronic back pain, and shoulder strains. Additionally, caregivers face risks from slip-and-fall accidents in wet client bathrooms or even injuries from unpredictable pets. In Nevada, carrying workers' compensation is legally required for businesses with employees. Beyond simple compliance, understanding the Workers' compensation basics for Nevada small businesses ensures that your injured staff members receive prompt medical care and lost wages while they recover, protecting your agency from direct employee lawsuits.
Commercial Auto Insurance
Transportation is a massive component of any home care operation. Your staff members spend a significant portion of their day driving from one client residence to the next. If your agency owns a fleet of vehicles used to transport clients to medical appointments or adult day care centers, you need a standard commercial auto policy.
However, most agencies rely on caregivers to drive their own personal vehicles. If an employee causes a severe accident while driving to a client's home, the injured party can sue your agency, arguing that the employee was acting within the scope of their employment. Because a personal auto policy will usually deny claims involving business use, your agency needs Hired and Non-Owned Auto coverage. Securing Small business car insurance: covering employees who drive is the only way to protect your balance sheet from catastrophic auto liability claims.
Cyber Liability Insurance
The home health industry has rapidly adopted new technologies to improve patient outcomes and streamline scheduling. By 2026, the use of remote patient monitoring devices, telehealth platforms, and cloud-based electronic health records has become the industry standard. While these tools improve efficiency, they also make your agency a prime target for cybercriminals. If a hacker breaches your database or a caregiver accidentally leaves a tablet containing protected health information at a coffee shop, your agency could face severe HIPAA violation fines, patient lawsuits, and mandatory notification costs. Cyber liability insurance provides the financial resources and technical support needed to navigate a data breach and restore your systems securely.
Managing Risk in a High-Stakes Environment
Having the right insurance policies in place is critical, but true protection comes from pairing those policies with aggressive, proactive risk management. At our agency, we review claims trends closely to help our clients prevent accidents before they happen.
One of the most pressing challenges facing the industry today is the labor shortage. Recent national industry reports indicate that caregiver turnover rates remain incredibly high, frequently hovering around 79 percent. When an agency experiences constant turnover, several risk factors multiply simultaneously. First, a revolving door of staff means that newer, less experienced caregivers are frequently interacting with clients, increasing the statistical likelihood of medication errors or improper lifting techniques. Second, when an agency is short-staffed, the remaining caregivers are forced to take on heavier workloads. Fatigue inevitably sets in, leading to a loss of focus, missed safety protocols, and a spike in both professional liability and workers' compensation claims.
To combat this trend, successful agency owners are investing heavily in retention strategies and workflow technology. Providing competitive compensation and robust Health insurance and employee benefits for Nevada small businesses is no longer optional if you want to keep reliable staff. Furthermore, forward-thinking agencies are using AI-driven scheduling assistants and mobile documentation platforms to reduce the administrative burden on caregivers. When staff members spend less time fighting with clunky software and more time focusing on the client, job satisfaction rises and careless errors drop.
From an underwriting perspective, insurance carriers look favorably upon agencies that take these proactive steps. When evaluating your application for insurance for home health care business operations, carriers want to see rigorous hiring protocols. They will ask about your background check procedures, your motor vehicle record auditing process, and your ongoing training programs. By proving that you actively manage your risks, you position your agency to secure better coverage limits at more favorable rates.
Actionable Insurance Checklist for Care Providers
Whether you are launching a new agency or preparing for your annual policy renewal, taking a systematic approach to your risk profile will save you time and money. We recommend that Nevada agency owners regularly review the following checklist to ensure their small business insurance coverage remains completely aligned with their operations.
- Audit Employee Classifications: The distinction between an independent contractor and a W-2 employee is heavily scrutinized by both the IRS and state labor boards. Misclassifying a caregiver to save on payroll taxes or workers' compensation premiums can lead to devastating fines and uninsured injury claims. Ensure your classifications are legally sound and accurately reported to your insurance carrier.
- Review Driver Records Annually: If your staff drives to client homes, their driving history is your liability. Implement a strict policy of pulling Motor Vehicle Records for every new hire and conducting annual reviews for all current staff. Establish clear, written guidelines detailing what types of traffic violations will disqualify an employee from driving on the job.
- Assess Your Liability Limits: Contractual requirements change frequently. Review the minimum insurance limits required by the Nevada Medicaid program, your private health insurance partners, and any referral networks you belong to. Carrying inadequate limits could result in a breach of contract or removal from a lucrative preferred provider list.
- Evaluate Your Technology Exposures: Take an inventory of every digital tool your agency uses, from payroll software to telehealth platforms. Verify that your cyber liability limits are high enough to cover a total system lockdown by ransomware, and ensure your staff receives regular training on how to spot phishing emails.
- Document Patient Refusals: In the home health sector, patients sometimes refuse necessary care or ignore medical advice, which can lead to negative health outcomes. Train your staff to meticulously document these refusals in the client's file. If a family later files a malpractice lawsuit claiming neglect, this documentation will be the foundation of your insurance defense.
Conclusion
Running a home care or home health agency is a demanding but incredibly rewarding calling. The work your team performs every day allows vulnerable members of our community to maintain their dignity, independence, and comfort. However, the inherent unpredictability of working inside private homes, coupled with a strict and evolving regulatory environment, means you simply cannot afford to take chances with your business protection.
By taking the time to understand the distinct differences between general and professional liability, addressing the physical risks to your staff, and implementing strong internal safety protocols, you create a foundation of stability. You cannot eliminate every hazard, but with the right preparation and the right partners, you can ensure that one unfortunate incident does not derail the business you have worked so hard to build.
Partner with Larry Peyton Insurance Agency
Finding the perfect insurance strategy does not have to be a stressful or confusing process. At Larry Peyton Insurance Agency, we bring over 100 years of combined industry expertise to the table, and our customers consistently love working with our remarkably friendly staff. We know that we cannot always control the insurance companies' rates, but we absolutely control how our clients are treated, ensuring you receive the respect, personalized attention, and highly responsive service you deserve. We are large enough to handle complex commercial workloads, yet small enough to truly care about your agency's unique mission.
Get a quote today and personalized assistance. Discover how we can help you achieve your goals by visiting our homepage. Let us protect your business, so you can continue protecting our community.
By Larry Peyton Farmers Insurance & Team
Your local, trusted, insurance professional.
Fast, friendly quotes from top-rated carriers.