
Personal Umbrella Insurance vs. Home and Auto Liability Limits
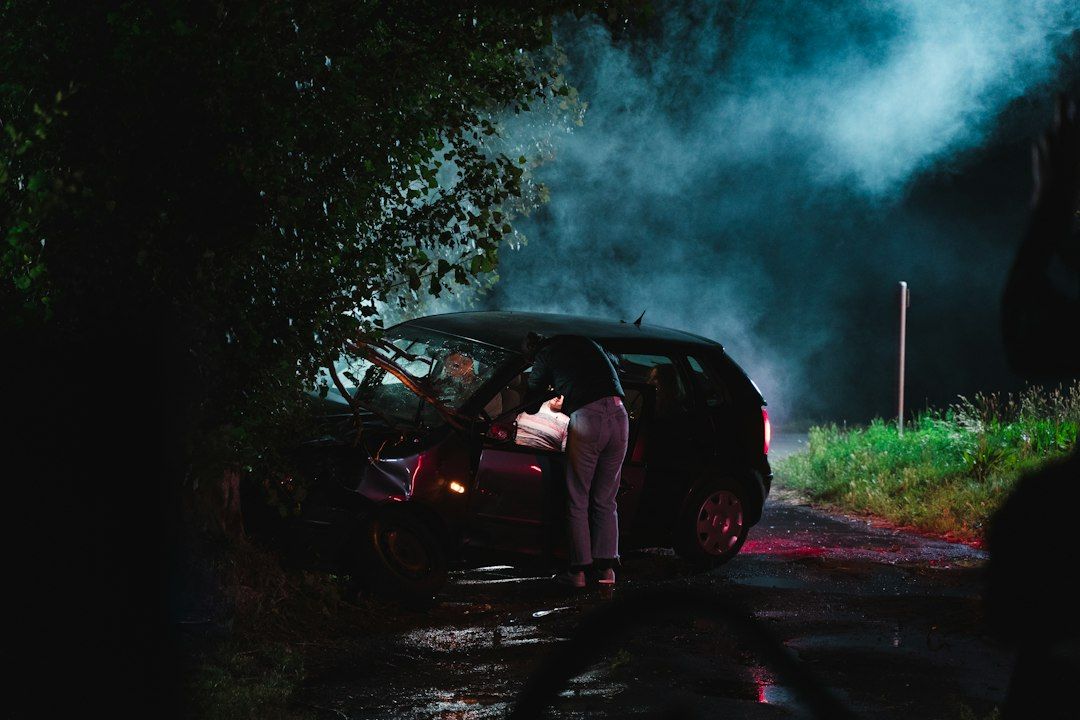
Imagine a rainy evening in Nevada. You’re driving home from work, momentarily distracted, and you slide into an intersection, causing a severe accident involving multiple vehicles. The medical bills, rehabilitation costs, and property damage quickly eclipse the liability limits on your auto policy.
Protecting Your Future from Unexpected Lawsuits
Imagine a rainy evening in Nevada. You are driving home from work, momentarily distracted, and you slide into an intersection, causing a severe accident involving multiple vehicles. The medical bills, rehabilitation costs, and property damage quickly eclipse the liability limits on your standard auto insurance policy. In that terrifying moment, your life savings, your home equity, and your future earnings are suddenly exposed to a massive lawsuit.
At Larry Peyton Insurance Agency, we have helped people find insurance for over 50 years. With over 100 years of combined expertise and the friendliest staff around, our customers consistently tell us they love working with our agency. We know that insurance is not just a mandatory expense; it is vital protection for everything you have worked so hard to build. Our mission is to deliver peace of mind by offering reliable, personalized insurance solutions that protect what matters most to our clients.
One of the most common vulnerabilities we see today is relying solely on standard home and auto liability limits. We regularly consult with clients who have accumulated significant assets but have not updated their liability safety nets to match their success. This article explores the critical differences between standard policy limits and the robust protection of a personal umbrella policy, ensuring you have the knowledge to safeguard your family and your future.
The Reality of Standard Liability Limits
When you purchase a standard auto or homeowners insurance policy, it comes with a built in cap on how much the insurance company will pay out in the event of a liability claim. For auto insurance, a common recommendation is to carry bodily injury limits of $250,000 per person and $500,000 per accident. For a homeowners policy, personal liability coverage typically ranges from $300,000 to $500,000.
A decade ago, those limits might have seemed more than adequate for a typical family. However, the legal and medical landscapes have shifted dramatically. Medical inflation has driven up the cost of emergency room visits, surgeries, and long term physical therapy. Vehicle repair costs have soared due to the expensive sensors and technology packed into modern cars.
More importantly, we are living in a highly litigious society. According to recent litigation trend reports from Marathon Strategies, the frequency of "nuclear verdicts" (jury awards exceeding $10 million) rose by 52 percent in 2024, with the median mega verdict amount pushing past $50 million. A separate study highlighted by Claims Journal noted that the average cost of defending personal injury lawsuits has been increasing at a steady annual rate. While you might not face a $50 million judgment, a $1 million or $2 million lawsuit resulting from a severe accident is no longer considered an outlier.
If a judge orders you to pay $1.5 million and your auto insurance caps out at $500,000, you are personally responsible for the remaining $1 million. The courts can force you to liquidate your savings, sell your investments, and they can even garnish your future wages for years to come. This is why choosing the right insurance in Reno and the surrounding Nevada communities requires looking beyond the bare minimums.
What Is an Umbrella Policy, and What Does It Cover?
When clients sit down in our office to review their coverage, one of the first questions they ask is, "What is an umbrella policy, and what does it cover?"
The simplest way to think about it is as a massive financial safety net that sits on top of your existing insurance policies. An umbrella policy provides an additional layer of liability coverage that kicks in only after the underlying limits of your primary auto, home, or watercraft policies have been completely exhausted.
For example, if you have a $500,000 liability limit on your auto insurance and you purchase a $1 million umbrella policy, you effectively have $1.5 million in total liability protection for covered auto accidents.
To qualify for an umbrella policy, insurance carriers generally require you to maintain specific minimum liability limits on your primary policies. This is one reason why we frequently help clients arrange auto and renters insurance bundles or home and auto packages, ensuring that all underlying policies meet the strict requirements of the umbrella carrier. If your underlying limits are too low, a gap in coverage could leave you financially responsible before the umbrella policy activates.
What Does a Personal Umbrella Policy Cover in Everyday Scenarios?
When discussing the specifics, clients want to know exactly how this coverage applies to real life. What does a personal umbrella policy cover when the unexpected happens? The coverage is surprisingly broad and falls into several vital categories.
Severe Bodily Injury Liability
This is the most common reason people rely on their umbrella coverage. If you are at fault in a major car crash, or if a guest suffers a severe injury at your home, the medical costs and subsequent lawsuits can be staggering. Imagine hosting a backyard barbecue where a guest slips near your swimming pool and suffers a traumatic brain injury. Your homeowner's limit of $300,000 could be depleted within the first few weeks of their hospitalization. The umbrella policy steps in to cover the remaining medical bills, lost wages, and pain and suffering judgments.
Extensive Property Damage
If you lose control of your vehicle and crash into a commercial storefront, or if you cause a multi car pileup involving several high end vehicles, the property damage can easily exceed a standard $100,000 auto property damage limit. An umbrella policy provides the extra funds needed to pay for the destruction of someone else's expensive property.
Personal Injury and Defamation
We live in an era of social media, online reviews, and digital communication. A standard auto policy will not help you if you are sued for libel or slander, and standard homeowners policies often have strict limits or exclusions regarding personal injury claims. An umbrella policy provides specialized protection against lawsuits involving defamation, libel, slander, false arrest, and malicious prosecution.
Landlord and Rental Liabilities
If you own a rental property, you face a unique set of risks. If a tenant or their guest falls down the stairs due to a loose handrail and decides to sue you, the liability can be immense. An umbrella policy extends over your landlord liability coverage, protecting your personal assets from lawsuits originating at your rental properties.
If you want to read an even more detailed breakdown of these specific coverages, we have a dedicated guide on what is an umbrella policy and what does it cover that explores these scenarios further.
What Does Personal Umbrella Insurance Cover Regarding Legal Fees?
Beyond the physical damages and medical bills, what does personal umbrella insurance cover that provides immediate relief during a lawsuit? The answer is legal defense costs.
Hiring a defense attorney to fight a prolonged liability lawsuit can cost hundreds of dollars per hour. It is not uncommon for legal fees alone to reach $50,000 to $100,000 or more before a case even goes to trial. One of the most powerful benefits of a personal umbrella policy is that it typically covers your legal defense costs in addition to the policy limit.
This means that if you have a $1 million umbrella policy and your insurance company spends $150,000 defending you in court, you still have the full $1 million available to pay the actual settlement or judgment. Knowing that a team of experienced defense lawyers is fighting for you, without draining your retirement accounts to pay their retainer, is the definition of true peace of mind.
The Value Proposition of Extra Protection
Our ideal customer at Larry Peyton Insurance Agency is someone in the 30 to 55 range. You likely own a home, have multiple vehicles in the driveway, and perhaps you have a boat or an RV for weekend trips. You might even own a business. You have worked hard to accumulate these assets, and you view insurance as a tool for genuine protection, not just another monthly bill.
Because you have built a successful life, plaintiff attorneys view you as someone with "deep pockets." If you have a teenage driver in the house, a swimming pool in the backyard, or a high net worth, your exposure to a devastating lawsuit is significantly higher than average.
When evaluating this risk, a common question we hear is, "What does umbrella liability insurance cover compared to its overall cost?"
Many people assume that purchasing a million dollars in coverage will cost a fortune. Fortunately, this is a misconception. Because the umbrella policy only kicks in after your primary policies have absorbed the initial financial impact, the statistical likelihood of the umbrella policy paying out is lower. This makes the coverage remarkably affordable.
Recent industry data for 2025 and 2026 shows that a standard $1 million personal umbrella policy typically costs between $200 and $600 per year. Adding a second million usually only adds another $75 to $150 to the annual premium. For roughly the cost of a few streaming service subscriptions, you can secure millions of dollars in liability protection.
We are the perfect sized agency for anyone looking for great coverage at a good price with wonderful service. We cannot always control the insurance companies' rates, but we can help you structure your personal insurance portfolio so that you receive the absolute best value for your hard earned money.
Exclusions and Limitations to Consider
To provide fair and objective advice, we must also look at the limitations of this coverage. When discussing what an umbrella policy covers, it is equally important to understand what it strictly excludes. An umbrella policy is not a magic wand that pays for everything.
First, an umbrella policy provides liability coverage, meaning it pays for damages you cause to others. It does not cover your own medical bills, nor does it pay to repair your own home or vehicle.
Second, it will not cover intentional or criminal acts. If you intentionally harm someone or willfully destroy their property, your insurance company will not protect you from the legal consequences.
Finally, a personal umbrella policy will not cover liabilities arising from your business or professional activities. If you are a small business owner and a client slips on the floor of your retail shop, or if your employee causes an accident while driving a company vehicle, your personal umbrella policy will deny the claim. To protect your company, you must purchase a separate commercial policy. We highly recommend reading our guide on using umbrella liability insurance to extend your business protection to ensure your professional assets are properly shielded.
Securing Your Peace of Mind
Relying exclusively on standard home and auto liability limits is a significant gamble in today's unpredictable legal climate. A single split second distraction on the road, or an unfortunate accident on your property, can instantly jeopardize everything you have worked so diligently to achieve.
At Larry Peyton Insurance Agency, we are large enough to handle the workload but still small enough to care deeply about the families we serve in Nevada. We pride ourselves on treating our clients with the utmost respect, ensuring they leave our office highly satisfied and fully educated about their risks. An umbrella policy is not a luxury reserved for the ultra wealthy; it is a fundamental building block of a secure financial plan for any family with assets to protect.
Partner with Larry Peyton Insurance Agency
Your family, your home, and your future deserve the highest level of protection. Do not wait for a life altering accident to find out that your standard liability limits were not enough. Our knowledgeable and friendly staff is ready to rise above the competition and provide you with the exceptional service you deserve.
Get a quote today and personalized assistance. Discover how we can help you achieve your goals. Let our team review your current coverage, identify any dangerous gaps, and custom build a personal umbrella policy that perfectly fits your unique lifestyle and budget. Contact Larry Peyton Insurance Agency today, and experience the profound peace of mind that comes from knowing you are truly protected.
By Larry Peyton Farmers Insurance & Team
Your local, trusted, insurance professional.
Fast, friendly quotes from top-rated carriers.